A client pays your invoice in cryptocurrency. You move the coins to another wallet, sell them weeks later and withdraw pounds to your bank. Several transactions now appear across your records, but they are not several payments for the same job.
The practical solution is to track two connected stories: payment for your work and what happens to the cryptoasset afterwards. A spreadsheet can do this, provided you preserve sterling values, transaction evidence and links between events. This guide focuses on UK recordkeeping; your accounting method and circumstances determine the eventual tax treatment.
Start with separate records for the work, the payment and the cryptoasset
Give each invoice a unique reference, then link the incoming crypto transaction to it. Keep subsequent wallet movements and sales in a separate transaction log. That prevents an exchange deposit, sale receipt or bank withdrawal from being mistaken for another client payment.
Financial-analysis software may help organise information, but broad product descriptions are not proof of crypto bookkeeping capability. For example, https://www.numevia.io/ advertises analysis of transactions, expenses and income, alongside reporting and forecasting. NUMEVIA’s Terms describe its current build as a front-end demo and state that outputs are not financial advice. Do not infer verified wallet imports, historical sterling valuations or UK tax calculations from those advertised capabilities.
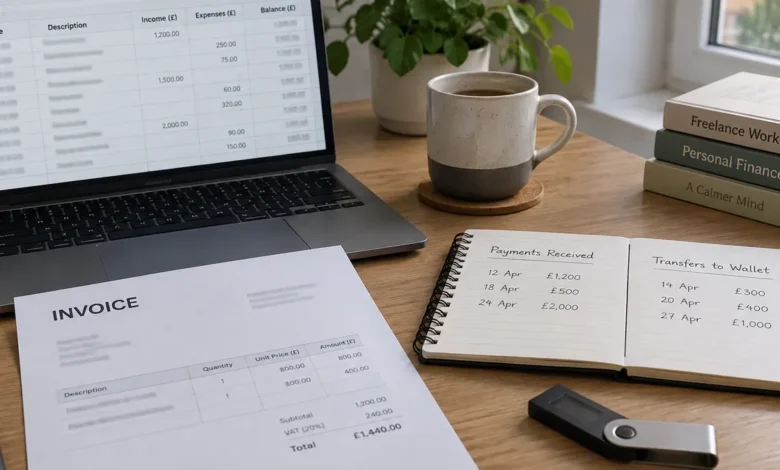
Start with three spreadsheet tabs: invoices, asset movements and an evidence index. The invoice tab records the client, work reference, invoice date, currency, amount due and settlement status. The movement log records what actually happened to the crypto. The evidence index points to saved invoices, exports and valuation records.
An invoice and its settlement are linked events, not automatically two income entries. Under cash-basis accounting, receipt generally drives recognition; under traditional accounting, income may already have been recognised before payment. Different valuation dates can also create accounting questions. Keep both dates and let your accountant apply the appropriate treatment rather than deleting one record to make totals match.
Record the GBP value and evidence when a client pays
For each payment, retain the token name, network, quantity, receipt date and time, receiving address or exchange account, transaction identifier and sterling valuation. Record the valuation source and its timestamp, including the time zone. A blockchain transaction proves a movement occurred; it does not, by itself, establish the correct GBP value.
Use a consistent, documented valuation method appropriate to the transaction. If the source quotes a dollar price, retain the dollar-to-sterling conversion evidence too. A stablecoin balance is not automatically worth the same number of pounds, and even its intended peg should not replace evidence of its value.
HMRC’s Check if you need to pay tax when you receive cryptoassets distinguishes tax on receiving cryptoassets from possible Capital Gains Tax when they are later disposed of. It also identifies useful records, including token type, receipt date, quantity, sterling value, bank statements and disposal details. Its payment-for-work section addresses employees, so a freelancer should not use that section alone to determine self-employment treatment.
Separate the amount invoiced from the amount delivered. A client may send too little, a processor may deduct a charge, or the agreement may specify a fixed token quantity instead of a fixed GBP amount. Record the gross settlement, any identifiable fee and any outstanding invoice balance. Do not silently treat every shortfall as an allowable expense.
- Save the invoice and the agreement specifying how crypto payment is valued.
- Retain transaction receipts, exchange exports and contemporaneous price evidence.
- Record fees separately, including their currency and who paid them.
- Mark partial payments and overpayments explicitly instead of forcing a full match.
Use one reference across these files. An accountant should be able to trace an invoice to the payment and its valuation without relying on your memory or a live exchange account.
Follow one payment through a wallet transfer and eventual sale
Consider a simplified example. You issue a £2,000 invoice and receive 0.05 BTC worth £2,000 when it arrives. Assume the invoice and receipt values agree, you have no other bitcoin holdings or relevant matching acquisitions, and transfer fees are excluded from this illustration.
- The work: record the £2,000 invoice under its unique reference.
- The payment: link the receipt of 0.05 BTC, valued at £2,000, to that invoice. Mark the invoice as settled rather than adding another unrelated £2,000 sale.
- The movement: record a transfer to another wallet you beneficially own. Link the outgoing and incoming entries as one internal movement.
- The sale: record gross proceeds of £2,200, a £20 selling fee and £2,180 net proceeds.
- The withdrawal: match the £2,180 bank receipt to the exchange withdrawal. It is not a fresh payment for the freelance work.
If this is a capital disposal, the £2,000 receipt value is the relevant allowable acquisition cost and the £20 selling fee qualifies, the illustrative gain is £180: £2,200 minus £2,000 minus £20. The £2,180 bank deposit is neither a second freelance fee nor the amount of the gain. A lower selling price could instead produce a loss.
Real calculations can differ. Existing holdings, same-day acquisitions and acquisitions within the following 30 days can affect which costs are matched to a disposal. UK pooling rules mean an invoice reference is useful evidence, not permission to choose a particular lot’s cost. Keep records across all wallets and exchanges, not just the account where you sold.
HMRC’s Cryptoassets Manual explains in CRYPTO22100 that transfers between wallets are not disposals where beneficial ownership remains unchanged. Selling, exchanging one token for another or spending tokens can be disposals even if no pounds reach your bank. CRYPTO22150 covers allowable acquisition and transaction costs and prevents deducting costs already deducted against Income Tax profits.
A network fee still needs its own record: moving your own assets does not make every associated fee irrelevant. Record the token quantity spent and GBP value, then obtain advice on its treatment. Similarly, not every later transaction necessarily falls under Capital Gains Tax; trading activity and other circumstances can change the analysis.
Check what an analysis tool can actually handle before sharing records
Test your spreadsheet process before adding automation. Use a small fictional dataset containing an invoice, a payment, an internal transfer, a fee and a sale. The tool should distinguish their roles, preserve your evidence references and flag uncertainty rather than invent missing prices or label every incoming transfer as revenue.
For the NUMEVIA example, the published support route at https://www.numevia.io/contacts provides a way to ask about suitability before submitting client records. The contact page offers support; it is not documentation confirming crypto imports, valuation methods, export formats or particular data-handling arrangements.
Ask whether your exact file format is supported, which transaction fields survive import, and whether original quantities and timestamps remain accessible. Establish whether values are supplied by you or generated by the service, and whether calculations can be traced to an identifiable source. A polished summary is not an audit trail.
Data handling deserves separate questions: what is retained, for how long, who can access it, and whether uploaded information is used for model training. Ask how deletion and exports work, and whether you can test with redacted data. Treat unanswered questions as unresolved rather than filling the gaps with assumptions.
Never provide seed phrases, private keys, passwords or withdrawal permissions for bookkeeping analysis. If a service supports account connections, confirm the permissions independently and prefer the least access necessary. Client names, invoice descriptions and wallet addresses can also expose sensitive commercial information, even without spending credentials.
Build a month-end evidence pack for your accountant
Reconcile each asset’s opening quantity, receipts, purchases, disposals, fees and closing quantity. Match both sides of internal transfers, allowing for separately recorded network fees. Investigate unmatched deposits: they could be client payments, purchases, rewards, returned funds or transfers from another account you own.
Then reconcile invoice balances and sterling movements independently. An unpaid invoice should remain visible even if your wallet balance has risen. A bank withdrawal should match an exchange record rather than being counted again as turnover. Download transaction histories regularly so your evidence does not depend on continued access to a platform.
Your month-end pack should contain the invoice register, asset-movement log, valuation evidence, fee records, exchange and bank statements, and a short list of unresolved items. Preserve original exports alongside any cleaned spreadsheet. If you correct an entry, note why instead of overwriting its history without explanation.
Ask your accountant to confirm the accounting basis, income recognition, treatment of fees and applicable disposal rules. Flag staking rewards, airdrops, DeFi activity and other receipts separately rather than mixing them into freelance settlements. The goal is a traceable chain from work performed to payment received to the asset’s eventual use or disposal—not a single total labelled “crypto income”.